

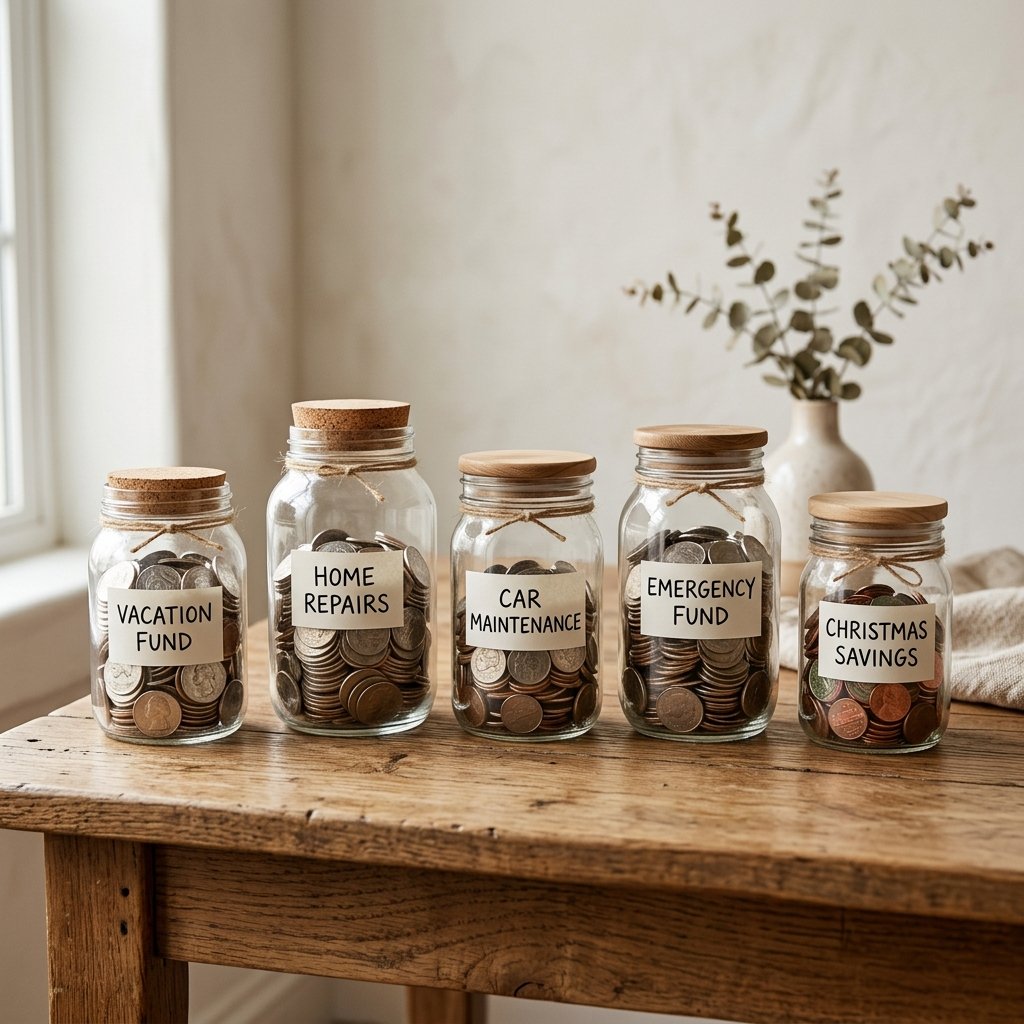
A sinking fund is money you set aside each month for a cost you know is coming, such as annual insurance, school fees, festival spending or a car service. Instead of paying a large bill all at once, or putting it on a credit card, you spread the cost across the year.
How a sinking fund works
- List the expenses that come once a year or less often.
- Estimate the cost of each one.
- Divide each amount by the number of months until it is due.
- Transfer that amount each month into a separate account or pot.
For example, if your annual insurance premium is 12,000, set aside 1,000 each month. When the bill arrives, the money is already there.
Sinking funds and emergency funds
These are different. An emergency fund covers surprises, such as job loss or urgent repairs. A sinking fund covers costs you can see coming. Keep them separate so that spending on a planned bill does not empty your safety net.
Common sinking fund categories
- Insurance premiums and vehicle registration
- Gifts, festivals and family events
- Holidays and travel
- Home maintenance, such as painting or appliance replacement
- Subscriptions that renew yearly
Keep it working
Review the fund every few months. If an estimate was too low, raise the monthly amount. If you spent less than planned, move the surplus to another category or to savings. A simple spreadsheet with one row per expense is enough.
Frequently asked questions
Where should I keep a sinking fund?
A separate savings account or a labelled sub-account is best, so the money is not mixed with your everyday spending.
Is a sinking fund the same as a budget?
No. A budget covers your monthly spending. A sinking fund is one part of a budget that prepares you for less frequent costs.
This article is for general information only and does not replace advice from a qualified financial adviser.